
Company Earnings Results: A Complete Guide to What Investors and F&O Traders Should Watch
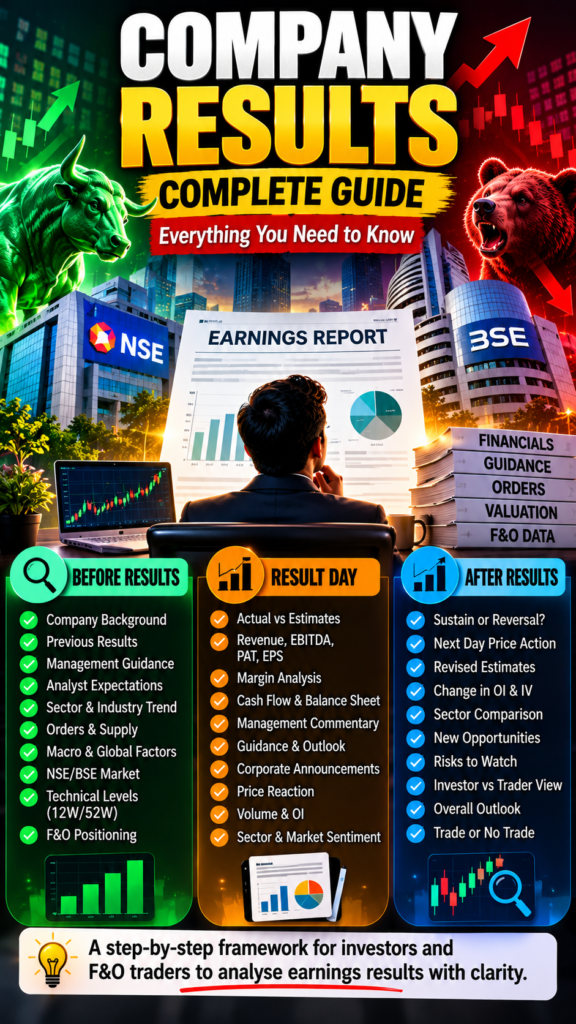
A quarterly earnings result is much more than a company announcing its revenue and profit.
For investors and traders, an earnings season brings together several moving parts—company performance, management commentary, sector trends, economic conditions, government policies, market expectations, institutional activity, technical levels and derivatives positioning.
A company can report strong profit growth and still see its stock fall. Another company can report weak numbers and see its share price rise.
Why?
Because the market does not react only to the result. It reacts to the difference between what the market expected and what the company actually delivered, along with what management says about the future.
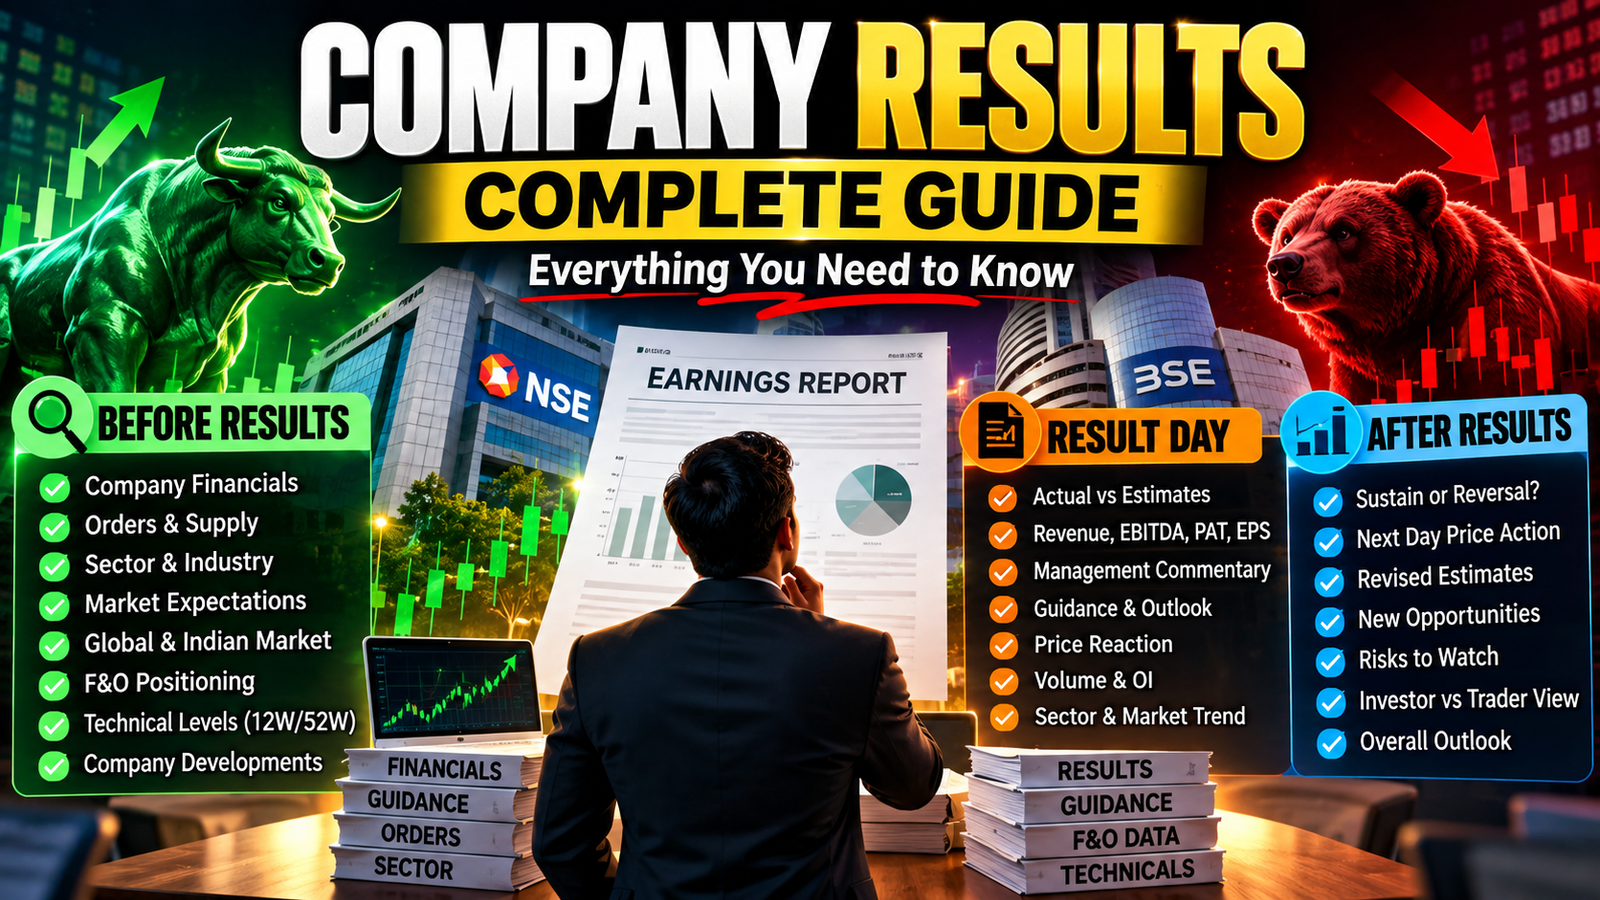
This guide explains a practical framework for analysing earnings before the result, on the result day, and after the result.
1. Start With the Business, Not the Numbers
Before looking at quarterly figures, understand what the company actually does.
Ask:
- What are its main products or services?
- Which segments generate most of its revenue?
- Is the business domestic or export-oriented?
- Who are its major customers?
- Who are its main competitors?
- Is the company cyclical or relatively stable?
- Is it dependent on commodities, interest rates, foreign currency or government spending?
- Is the stock available in the F&O segment?
This basic understanding helps put the quarterly numbers into context.
A 10% revenue decline can mean very different things for a seasonal business compared with a company operating in a steady-demand industry.
2. Study the Previous Results
One quarter should never be analysed in isolation.
Ideally, review the company’s previous 4–8 quarterly results and look for trends in:
- Revenue
- EBITDA
- EBITDA margin
- Profit after tax
- EPS
- Operating cash flow
- Debt
- Working capital
- Segment performance
- Order book
The objective is not simply to find whether profit increased.
The bigger question is:
Is the underlying business improving consistently, or is this quarter an exception?
For example, if PAT has increased for one quarter because of a one-time gain, that is very different from sustained improvement in operating profit and cash flow.
3. Previous Earnings and Conference Calls Matter
Management commentary from previous earnings calls can provide valuable context.
Look at what management previously said about:
- Revenue growth
- Margins
- Demand
- Order book
- Capex
- Pricing
- Raw-material costs
- Hiring
- New products
- Future risks
Then compare the previous guidance with what actually happened.
A simple exercise:
Previous management guidance → Actual outcome → Current guidance
This helps identify whether management’s earlier expectations were broadly achieved and whether the current outlook has changed.
The analyst Q&A section of an earnings call can also be useful because questions often focus on demand, margins, competition, pricing and risks.
4. Market Expectations Are Extremely Important
This is one of the most important concepts in earnings analysis.
Do not ask only:
“Was the result good?”
Also ask:
“Was the result better or worse than what the market expected?”
Suppose analysts expected:
- Revenue: ₹10,000 crore
- PAT: ₹1,000 crore
Actual result:
- Revenue: ₹10,500 crore
- PAT: ₹1,100 crore
The headline result looks strong.
But if the market was expecting PAT of ₹1,200 crore, the same ₹1,100 crore result could be considered disappointing relative to expectations.
That is why:
Actual Result vs Market Expectation
is often more important for short-term price reaction than:
Actual Result vs Previous Quarter.
5. Earnings Revisions
Before the result, check whether analysts have been:
- Increasing EPS estimates
- Reducing EPS estimates
- Increasing revenue estimates
- Reducing margin expectations
Also look at forward-year estimates where reliable data is available.
For example:
FY27 EPS estimate:
₹50 → ₹55
shows an upward revision.
But:
₹50 → ₹43
shows a downward revision.
The current quarterly result should therefore be viewed alongside the market’s changing expectations for future earnings.
6. Revenue, EBITDA, Margin, PAT and EPS
These are the core financial numbers.
Revenue
Shows the scale of business activity.
Look at:
- YoY growth
- QoQ movement
- Volume growth
- Pricing impact
EBITDA
Helps understand operating performance before interest, taxes, depreciation and amortisation.
EBITDA Margin
Often more informative than revenue growth alone.
For example:
Revenue ↑ 12%
EBITDA ↑ 20%
Margin ↑
This may indicate improving operating leverage or pricing/cost benefits.
PAT
Look at both growth and quality.
EPS
Important for valuation and earnings expectations, particularly for listed companies.
7. Don’t Ignore Cash Flow and Balance Sheet
A company can report strong accounting profit while its cash generation remains weak.
Check:
- Operating cash flow
- Free cash flow
- Receivables
- Inventory
- Payables
- Debt
- Interest cost
Ask:
Is the company converting accounting profits into cash?
Also investigate unusual movements in working capital.
8. Order Book, New Orders and Supply
For companies where orders drive future revenue, this can be one of the most important areas.
Look at:
- New order inflow
- Order book
- Order execution
- Order-to-revenue ratio
- Order cancellations
- Large customer contracts
- Production
- Dispatches
- Capacity utilisation
- Supply constraints
Industries such as infrastructure, defence, capital goods, engineering and certain manufacturing businesses can be particularly sensitive to order visibility.
However, an order announcement should not automatically be treated as guaranteed future revenue. Execution timelines, margins, financing and cancellation risks also matter.
9. Company-Specific Changes
Between two quarterly results, major changes can occur inside a company.
Check for:
- CEO/CFO or key management changes
- Promoter stake changes
- Acquisitions
- Mergers
- Demergers
- New products
- New plants
- Capacity expansion
- Plant shutdowns
- Major customer wins/losses
- Regulatory approvals
- Regulatory actions
- Fund raising
- Buybacks
- Dividends
- Bonus or stock splits
Sometimes the stock reacts more strongly to one of these developments than to the quarterly numbers themselves.
10. Sector Analysis
Never analyse a company completely in isolation.
Study the sector first.
Look at:
- Sector index performance
- Competitor results
- Industry demand
- Pricing environment
- Competition
- Capacity
- Commodity costs
- Regulation
- Industry growth
Example
For an IT company, relevant factors may include:
- US technology spending
- BFSI demand
- Deal wins
- Client budgets
- Attrition
- USD/INR
For a bank:
- Credit growth
- Deposit growth
- NIM
- CASA
- Slippages
- GNPA/NNPA
- Provisioning
For an auto company:
- Monthly sales
- Volumes
- ASP
- Discounts
- Rural demand
- EV demand
The relevant factors change from sector to sector.
11. Seasonality Matters
Quarter-on-quarter comparison can sometimes be misleading.
Certain industries naturally perform better in specific quarters.
Examples include:
- Auto — festive demand
- Hotels — travel seasons
- Aviation — travel demand and fuel environment
- FMCG — festive/rural demand
- Cement — construction cycle and weather
- Agriculture-related businesses — crop and monsoon cycles
Therefore, compare:
Current quarter vs previous quarter
and
Current quarter vs same quarter last year
while also considering the company’s historical seasonal pattern.
12. Inflation
Inflation can influence:
- Input costs
- Consumer demand
- Employee costs
- Margins
- Interest rates
- Borrowing costs
Track relevant indicators such as CPI and WPI, but always connect them to the company’s actual business model.
13. Crude Oil
Crude oil can be an important earnings driver for several industries.
Potentially sensitive sectors include:
- Aviation
- Paints
- Tyres
- Chemicals
- Logistics
- Oil marketing
- Refining
But the impact is not automatically positive or negative for every company.
The important question is:
Does the company benefit from higher crude prices, suffer from them, or have partial protection through pricing/pass-through mechanisms?
14. Currency and Interest Rates
USD/INR
Particularly relevant for:
- IT exporters
- Pharma exporters
- Import-heavy businesses
- Aviation
- Oil-related companies
Interest rates
Track:
- RBI policy
- Fed policy
- Repo rate
- Bond yields
- Credit conditions
These can be especially relevant for:
- Banks
- NBFCs
- Real estate
- Auto
- Capital-intensive businesses
15. Government Announcements and Policy
Government decisions can directly change the earnings outlook of certain sectors.
Watch for:
- Budget announcements
- Tax changes
- Import/export duties
- Tariffs
- PLI schemes
- Subsidies
- Infrastructure spending
- Government capex
- Sector regulations
- Government tenders
- Policy changes
A company can report a good quarter while a new policy changes its future earnings outlook.
16. Global Markets and Geopolitics
Indian companies are increasingly influenced by global markets.
Before major earnings events, monitor:
- S&P 500
- Nasdaq
- Dow Jones
- Asian markets
- European markets
- GIFT Nifty
- US Treasury yields
- DXY
- Brent crude
- Gold
- Other relevant commodities
Also consider major geopolitical developments, trade restrictions, sanctions and supply-chain disruptions where relevant to the company.
17. Overall Indian Market — NSE and BSE
A stock’s reaction does not happen in isolation.
NSE
Monitor:
- Nifty 50
- Bank Nifty
- Nifty Midcap
- Nifty Smallcap
- India VIX
- Market breadth
- FII/DII activity
- Nifty futures
- Major support/resistance
BSE
Useful broader-market references include:
- Sensex
- BSE 500
- BSE MidCap
- BSE SmallCap
- Sector indices
- Market breadth
- Volume
For F&O trading, NSE derivatives data will generally be the primary reference when the relevant contract is listed there.
18. Technical Position Before Results
Before the announcement, understand where the stock is trading.
Check:
- Daily trend
- Weekly trend
- 12-week high
- 12-week low
- 52-week high/low
- Previous result high/low
- Major support
- Major resistance
- Gap levels
- Volume
- VWAP where relevant
Example
If a stock is already close to its 12-week high before results, a strong result may trigger a breakout.
But if the result is strong and the stock fails to break that resistance, the market’s reaction needs further investigation.
Technical levels are context, not guarantees.
19. F&O Positioning Before Results
For F&O stocks, analyse derivatives separately.
Futures
- Futures price
- Spot-futures difference
- Futures OI
- Price + OI relationship
Options
- Call OI
- Put OI
- Change in OI
- PCR
- IV
- Option volume
- Important strikes
- Expiry
- Expected move
Also understand the difference between:
Long buildup
Short buildup
Short covering
Long unwinding
These are positioning observations, not guaranteed directional signals.
20. Implied Volatility and Expected Move
This becomes especially important around results.
Options can become expensive before a major event because traders anticipate higher volatility.
Therefore:
Correct direction does not automatically guarantee an options profit.
IV can change sharply after the announcement.
The expected move derived from options pricing can be used as a reference for what volatility is being priced into the stock—not as a guaranteed prediction.
🔴 RESULT DAY
Now comes the most important part.
Step 21: Compare Actual vs Estimate
Create a simple table:
| Metric | Estimate | Actual | Difference |
| Revenue | — | — | — |
| EBITDA | — | — | — |
| Margin | — | — | — |
| PAT | — | — | — |
| EPS | — | — | — |
Classify the result as:
Beat / broadly in line / miss
But don’t stop there.
21. Earnings Quality
If PAT is sharply higher, investigate why.
Was it because of:
- Core operating improvement?
- Other income?
- Tax benefit?
- One-time gain?
- Exceptional item?
- Asset sale?
- Lower provisions?
This distinction can materially change the interpretation of the result.
22. Management’s New Guidance
After the numbers, focus on the future.
Look for changes in:
- Revenue guidance
- Margin guidance
- Demand outlook
- Order book
- Capex
- Pricing
- Costs
- Hiring
- Expansion
- Risks
The key question:
Has management become more optimistic, less optimistic, or broadly unchanged compared with the previous call?
23. The Most Important Event: Price Reaction
This is where many traders make mistakes.
Suppose:
PAT +30%
but stock falls 5%.
Don’t immediately assume the market is wrong.
Investigate:
- Was +30% already expected?
- Was valuation expensive?
- Was guidance weak?
- Were future estimates reduced?
- Was there profit booking?
- Was the whole sector weak?
- Was the overall market falling?
- Was there heavy short positioning?
The market reaction itself is information.
24. Result-Day Price + Volume + OI
After the announcement, watch:
Price
↓
Volume
↓
VWAP
↓
OI
↓
IV
↓
Support/Resistance
↓
Sector
↓
Nifty
This gives a much better picture than looking at the result headline alone.
25. Next Trading Session Matters
Don’t assume the first reaction is the final reaction.
Observe the next session:
Gap-up
Does it sustain?
Gap-down
Does it recover?
High volume
Is participation continuing?
VWAP
Does price remain above/below it?
OI
Is fresh positioning developing or is existing positioning being unwound?
Sector
Is the whole sector moving in the same direction?
This can help distinguish an initial reaction from a more sustained market response.
26. Investor vs F&O Trader
This distinction is extremely important.
For an Investor
Focus more on:
Business quality → earnings growth → cash flow → debt → valuation → future growth → management
Time horizon:
Months/years
For an F&O Trader
Focus more on:
Expectation → earnings surprise → guidance → market regime → price reaction → OI → IV → technical confirmation → risk
Time horizon:
Minutes/days/weeks
A great long-term company does not automatically mean a good short-term F&O trade.
27. The Complete Earnings Flow
The entire process can be simplified into one chain:
GLOBAL MARKET
↓
Global indices | Yields | DXY | Crude | Commodities
MACRO
↓
Inflation | RBI | Fed | Currency | Government policy | Geopolitics
INDIA MARKET
↓
Nifty | Bank Nifty | Sensex | VIX | Breadth | FII/DII
SECTOR
↓
Demand | Competition | Seasonality | Commodity | Regulation
COMPANY HISTORY
↓
Previous results | Conference calls | Guidance vs actual
CURRENT BUSINESS
↓
Orders | Supply | Production | Customers | Capex | Capacity
EXPECTATIONS
↓
Consensus | EPS revisions | Valuation | Price-in
CURRENT RESULT
↓
Revenue | EBITDA | Margin | PAT | EPS | Cash flow
FUTURE
↓
Management guidance | Order book | Earnings outlook
F&O
↓
OI | PCR | IV | Expected move | Futures
TECHNICAL
↓
12W high/low | 52W high/low | VWAP | Volume | Support/Resistance
MARKET REACTION
↓
Price + Volume + OI + Sector + Overall Market
FINAL DECISION
Trade / No Trade
28. One Rule We Should Never Forget
A result can be:
Fundamentally strong
but
technically weak.
A stock can be:
Fundamentally weak
but
short-term bullish because expectations were even worse.
And an option can be:
directionally correct
but still lose money because of IV contraction, time decay or poor entry.
That’s why no single indicator should control the entire decision.
Final Takeaway
A professional earnings analysis is not simply:
“Profit बढ़ा = Buy.”
It is:
Past performance + management commentary + expectations + sector + seasonality + macro + orders/supply + company developments + valuation + market positioning + F&O + technicals + actual result + guidance + price reaction.
And the most important principle is:
Result → Expectation → Surprise → Guidance → Price Reaction
This framework is designed to help investors and traders understand the market rather than predict it with certainty.
⚠️ Financial Disclaimer
The information and analysis presented in this article are for educational and informational purposes only and do not constitute investment, financial, or trading advice.
Investing and trading, particularly Futures & Options (F&O), involve substantial risk and may result in significant or complete loss of capital. Past performance does not guarantee future results, and no strategy can guarantee profits.
Readers should independently verify information through official sources such as NSE, BSE, SEBI and company filings and consider consulting a SEBI-registered investment adviser before making financial decisions.
Invest responsibly. Do your own research. Trade only according to your risk capacity.